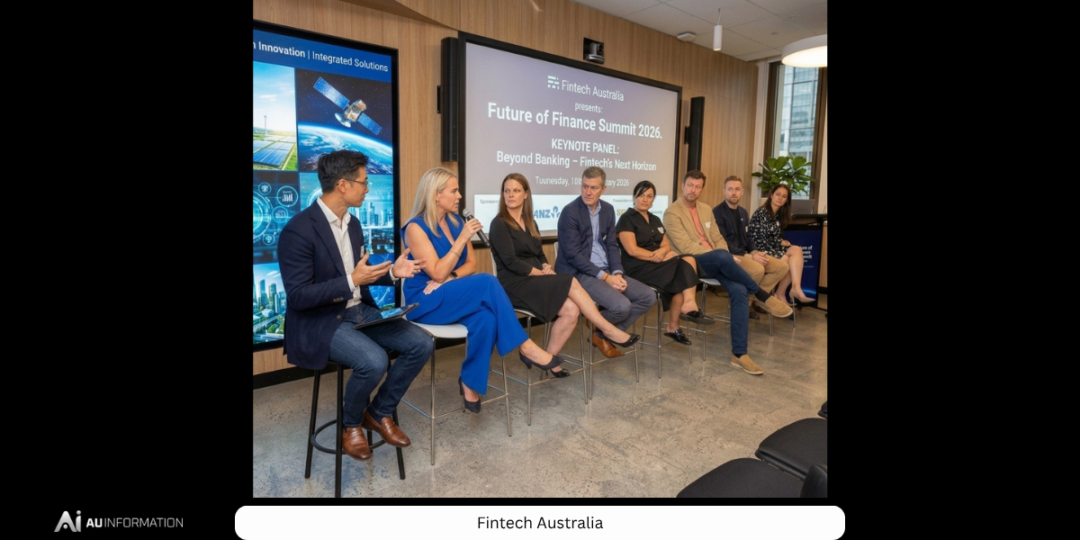
Australia’s financial services industry is undergoing a significant transformation, and FinTech Australia sits at the center of that change. From instant digital payments and open banking to artificial intelligence, digital lending, and financial inclusion, fintech is changing how Australians save, borrow, invest, insure, and manage money.
The scale of the sector is now substantial. FinTech Australia represents more than 400 fintech companies and startups, while the broader Australian fintech ecosystem contains more than 800 businesses across 13 subsectors. According to FinTech Australia’s 2026 landmark industry report, the sector contributed approximately $13.6 billion directly to Australia’s economy during 2024–25, equivalent to around 0.5% of national GDP, while directly employing approximately 50,200 people.
These figures demonstrate that fintech is no longer simply a collection of ambitious startups challenging traditional banks. It has become an established component of Australia’s technology and financial-services economy.
What Is FinTech Australia?
FinTech Australia is the national industry association representing Australia’s fintech sector. Its role extends beyond promoting individual technology companies.
The organization works across areas such as
- Industry advocacy
- Policy development
- Government engagement
- International expansion
- Industry research
- Networking
- Startup support
- Fintech events and awards
Its broader purpose is to help build an environment in which Australian financial technology businesses can develop, compete internationally and contribute to economic growth.
This matters because fintech companies operate at the intersection of two highly regulated industries: technology and financial services. Successful innovation therefore requires not only good software but also an understanding of regulation, consumer protection, cybersecurity and financial risk.
How Large Is Australia’s Fintech Industry?
Australia has developed a remarkably diverse fintech ecosystem.
The sector covers more than a dozen subsectors, including:
Digital Payments
Payment technology has become one of Australia’s most visible fintech success stories. Consumers increasingly expect transactions to be immediate, convenient and secure.
Lending
Digital lenders use technology and alternative data to streamline loan applications and credit assessment.
WealthTech
Wealth technology platforms are making investing, financial planning and portfolio management increasingly accessible through digital platforms.
InsurTech
Insurance technology companies are using digital platforms, automation and data analytics to improve insurance distribution and customer experience.
RegTech
Regulatory technology helps financial institutions manage compliance, reporting, monitoring and risk more efficiently.
Digital Identity
Digital identity technology is becoming increasingly important as financial institutions seek safer ways to verify customers and prevent fraud.
This diversity is one of the major strengths of the Australian fintech ecosystem.
FinTech Australia’s Economic Contribution
One of the clearest signs of fintech’s maturity is its growing economic contribution.
FinTech Australia’s 2026 landmark report estimates that Australian fintech generated $13.6 billion in direct economic contribution during 2024–25 and supported approximately 50,200 direct jobs.
The report also presents an ambitious long-term outlook, estimating that the industry could reach approximately $37 billion in annual direct economic contribution by 2035 if the ecosystem continues to expand.
That potential depends on several factors, including access to capital, regulation, international expansion, technological innovation and the ability of Australian companies to scale beyond the domestic market.
Australian Fintech Is Becoming More Mature
The current Australian fintech market looks considerably different from the startup environment of a decade ago.
FinTech Australia’s 2026 data indicates that approximately 88% of fintech respondents were generating revenue, while around 43% were profitable.
This is an important shift.
Early fintech markets are often dominated by companies focused on user growth and venture funding. As markets mature, investors and founders increasingly prioritise sustainable economics.
However, the data also suggests that the environment for very young startups has become more difficult.
Higher funding expectations, stronger competition and increasing regulatory complexity mean that simply having an innovative financial application is no longer enough.
A successful fintech increasingly needs:
- A genuine customer problem
- A scalable business model
- Strong compliance
- Reliable technology
- Cybersecurity
- Sustainable customer acquisition
- A pathway to profitability
Artificial Intelligence Is Reshaping Australian Fintech
Artificial intelligence is becoming one of the most important technologies influencing financial services.
Australian fintech companies can use AI for everything from customer service and fraud detection to credit assessment and financial analysis.
Potential applications include:
- Fraud detection
- Transaction monitoring
- Personalised financial recommendations
- Automated compliance
- Customer support
- Credit-risk analysis
- Financial forecasting
- Identity verification
- Document processing
The opportunity is significant, but so are the risks.
Financial organisations handle highly sensitive information. AI systems therefore need appropriate governance, security, transparency and human oversight.
The future of Australian fintech is unlikely to involve AI simply replacing employees. Instead, the strongest businesses are likely to use AI to automate repetitive tasks while allowing professionals to concentrate on more complex financial and customer decisions.
Digital Payments Remain a Major Growth Area
Australians have rapidly adopted digital payment methods, creating fertile ground for fintech innovation.
Consumers increasingly expect to pay through:
- Mobile wallets
- Digital banking applications
- Instant transfers
- Contactless payments
- Embedded payment systems
- Online checkout platforms
Australian fintech companies are consequently competing not only with banks but also with global technology companies and international payment providers.
The 2026 Finnies Awards highlighted businesses such as Zepto and Hello Clever, demonstrating the continued strength of innovation in Australia’s payments ecosystem.
Open Banking and Consumer Data
Open banking is another major component of Australia’s fintech future.
The principle is straightforward: consumers should have greater control over their financial information and be able to authorise its secure sharing with accredited organisations.
This can allow fintech platforms to develop services that provide consumers with more personalised financial products.
For example, an application could potentially analyse authorised financial information to help users:
- Compare financial products
- Track spending
- Identify recurring expenses
- Improve budgeting
- Assess borrowing options
The long-term value of open banking will depend heavily on consumer trust. People are unlikely to embrace data-sharing systems if they do not understand who can access their information or how it will be used.
Leading Names in the Australian Fintech Ecosystem
Australia’s fintech industry contains companies operating across very different parts of financial services.
The 2026 Finnies Awards provided a useful snapshot of this diversity, highlighting companies including:
- Zepto — payments
- Hello Clever — digital payments and financial technology
- Remitly — international money transfers
- RedOwl — financial technology and risk-related innovation
- Block Earner — digital financial services
- upcover — InsurTech
- Otivo — digital financial advice
These businesses demonstrate that Australian fintech is not defined by one particular product.
The ecosystem stretches from payments and remittances to insurance, digital assets, financial advice and compliance technology.
The Challenge of International Expansion
Australia has a relatively small domestic population compared with major markets such as the United States, China and Europe.
For fintech founders, this creates an important strategic question: How do you build a global company from Australia?
International expansion can provide enormous opportunities, but it introduces additional challenges.
A fintech expanding overseas may need to navigate:
- Different financial regulations
- Licensing requirements
- Currency systems
- Tax rules
- Consumer behaviour
- Banking partnerships
- Data regulations
- Local competitors
Australian fintech companies that successfully solve these challenges can turn the country’s relatively small domestic market into a launching pad for international growth.
Revolut Adds Competitive Pressure
The competitive landscape is also changing as international fintech companies expand their Australian operations.
Revolut has been increasing its presence in Australia and considering further expansion into products such as mortgages.
This matters because Australian banking has historically been dominated by a small number of major institutions.
New technology-focused competitors can put pressure on established banks to improve:
- Digital experiences
- Pricing
- Product innovation
- Customer service
- Payment functionality
- Personalisation
Competition can ultimately benefit consumers, provided innovation develops alongside strong regulatory protections.
Fintech Jobs in Australia
The growth of fintech is also creating employment opportunities across technology and finance.
Potential roles include:
- Software engineers
- Data scientists
- AI specialists
- Cybersecurity professionals
- Product managers
- Compliance specialists
- Financial analysts
- Risk professionals
- UX designers
- Regulatory technology experts
The most valuable professionals are increasingly those who can combine technical knowledge with financial-services expertise.
For example, an AI engineer who understands financial regulation may be more valuable to a fintech company than someone with purely technical experience.
Common Mistakes in Fintech
The fintech sector offers enormous opportunities, but several mistakes can undermine otherwise promising businesses.
Ignoring Regulation
Financial technology companies cannot treat compliance as an afterthought.
Prioritising Growth Over Economics
Millions of users do not guarantee a sustainable business if customer acquisition costs are excessive.
Underestimating Cybersecurity
A single serious breach can destroy customer trust and cause substantial financial and regulatory damage.
Building Technology Without Solving a Real Problem
Innovation only matters when it improves the customer’s financial experience or solves a genuine market problem.
Treating AI as a Substitute for Governance
AI can improve efficiency, but financial decisions require appropriate controls, transparency and accountability.
What Should Fintech Founders Focus On?
For entrepreneurs considering Australia’s fintech market, several principles are particularly important.
Solve a specific problem. Avoid building a product simply because a technology is fashionable.
Build compliance early. Regulatory requirements should influence the product architecture from the beginning.
Protect customer data. Security should be part of the product rather than an additional feature.
Measure economics. Track customer acquisition costs, retention, revenue and profitability.
Design for scale. Consider international requirements before technology becomes difficult to adapt.
Use AI responsibly. Automation can be powerful, but financial decisions require appropriate safeguards.
The Future of FinTech Australia
The next decade could be transformative for Australia’s fintech industry.
AI will likely become embedded across financial products and operational systems. Digital payments will continue evolving, while open banking could provide consumers with more control over their financial data.
At the same time, cybersecurity, digital identity and regulatory technology will become increasingly important as financial services become more digital.
FinTech Australia’s projected $37 billion annual direct economic contribution by 2035 illustrates the scale of the opportunity.
However, future growth will depend on whether Australian fintech companies can move from innovation to sustainable scale.
The companies that succeed are likely to be those that combine technology with financial expertise, regulatory discipline and a clear understanding of customer needs.
Conclusion
FinTech Australia represents one of the most dynamic intersections between technology and financial services in the country’s economy. With more than 800 fintech businesses across multiple subsectors, tens of thousands of direct jobs and a reported $13.6 billion direct economic contribution, the industry has moved well beyond its startup origins.
The next stage will be defined by artificial intelligence, digital payments, open banking, cybersecurity, financial inclusion and international expansion.
Australia already has the talent, technology and entrepreneurial capability to produce globally competitive fintech companies. The challenge is scaling those businesses while maintaining consumer trust, regulatory compliance and financial sustainability.
For consumers, that competition promises more choice and increasingly personalised financial services. For entrepreneurs and technology professionals, it creates a growing market filled with opportunities.
The most important development, however, is that fintech is no longer simply changing the way Australians use financial services. It is increasingly becoming part of the infrastructure through which modern Australian commerce operates.

No Comments